Table of contents19 sections
- Introduction
- Revenue
- Costs
- Profit, in the simplest terms, is revenue minus costs
- Margin
- Profitability
- Cash flow
- Financial liquidity
- Receivables
- Payables
- Working capital
- DSO, the average time spent waiting for payment
- Cash gap
- Output VAT and input VAT
- Depreciation
- Financial result versus account balance
- How Administy organises this data
- Summary
- Important information
Anyone can run a company. You do not need to be an accountant or a CFO, or to have a degree. But to manage a company well day to day, it is worth understanding the basic financial mechanisms and the environment the company operates in.
It is important to know what affects the condition of the company, where the business currently stands, what can be improved, which ratios are worth watching, how to interpret them and how to control financial flows, that is, cash flow.
Of course, many external factors affect a company’s condition, from both its closer and its wider environment. All the more reason to understand the basic financial concepts that help you judge whether the business really earns money, has money and is able to pay its obligations on time.
Turnover or the bank account balance alone is not enough for a reliable assessment of a company’s condition.
Revenue
The first of them is revenue, often confused with income.
Revenue is the value of the company’s sales in a given period. If we issue invoices totalling 10,000 PLN net, our revenue is 10,000 PLN.
Revenue is not, however, the same as money arriving in the account. A company can report revenue even though the client has not yet paid the invoice. That is why revenue is not just the bank account balance, that is, the money the company already has in its account, but also the amounts due, for example from invoices issued to clients that have not yet been paid.
This is one of the basic differences worth understanding at the start: revenue does not yet mean money in the account, it is the total value of sales in a given period.
Costs
Costs are all the expenses and use of resources connected with running the business and generating revenue.
In a service company they can include, among other things:
- salaries,
- subcontractors,
- software,
- marketing,
- the office,
- accounting,
- cars,
- external services.
It is worth analysing not only the company’s total costs, but also the costs of specific projects, clients and departments.
Profit, in the simplest terms, is revenue minus costs
A company can have high revenue and very low profit at the same time if the costs of delivering the sales are high.
An example: you run a service company and deliver a project worth 100,000 PLN. At first you assumed a margin of 45%, so the planned profit was to be 45,000 PLN.
During the project, however, it turned out that you needed more materials, additional hours from the team or help from subcontractors. Costs rose and the margin fell from 45% to 10%.
In the end, instead of the planned 45,000 PLN of profit, the project brought in only 10,000 PLN.
Sales were still 100,000 PLN, but the project’s financial result was much worse than planned.
That is why growth in sales does not always mean an improvement in the financial situation.
Margin
The next definition is your Holy Grail, and we are talking about margin.
You run a company, you sell services, but you want to know exactly how much you actually earn on a specific service or project?
Margin shows what part of revenue remains after deducting specified costs.
An example:
- A project was sold for 20,000 PLN and delivering it cost 14,000 PLN.
- The profit on the project is 6,000 PLN, so the margin is 30%.
Margin is especially important in service companies, because extra hours of work, revisions or subcontractor costs can gradually erode it.
Profitability
Profitability answers the question: is the company, client or project really worth it?
You can analyse, among other things:
- the profitability of the whole company,
- the profitability of a project,
- the profitability of a client,
- the profitability of a product or service.
The client generating the highest sales does not have to be the most profitable, if serving them takes a lot of work and generates high costs.
Cash flow
Cash flow shows the actual inflows and outflows of money in the company.
It is one of the most important areas a business owner should control.
A company can generate a profit and at the same time have a liquidity problem, because clients have not yet paid the invoices issued to them.
An example:
You have issued invoices for services delivered, totalling 45,000 PLN, with a 14-day payment term. 21 days pass and the money is still not in the account.
At the same time you have to pay for the office, materials, subscriptions and licences, and pay salaries.
On paper the company may report a good result, but the account starts to run short. In practice you start financing your clients with your own money.
That is why you need to distinguish between:
- the financial result, which shows how much the company has earned,
- cash flow, which shows how much money has actually come into and gone out of the company.
Financial liquidity
Financial liquidity means a company’s ability to pay its obligations on time. In practice it comes down to the question: will the company have enough funds to pay salaries, taxes, suppliers and other costs?
A lack of liquidity can be a problem even in a profitable company (high profit on invoices, but no money in the bank account).
Receivables
Receivables are money that others should pay your company.
Most often these are sales invoices that have been issued but not yet paid.
It is worth monitoring:
- the value of all receivables,
- overdue receivables,
- the number of days of delay,
- clients who regularly pay late.
A high level of receivables means that part of the company’s money is in fact with its clients, and you start financing your clients with your own money.
Payables
Payables are funds that your company should pay to other entities.
They can include:
- supplier invoices,
- salaries,
- taxes,
- contributions,
- loan and lease instalments.
Comparing receivables and payables helps assess the company’s future cash position.
Working capital
Working capital shows what part of its funds remains with the company to finance day-to-day operations after short-term payables are taken into account. It is money you can reinvest in your company.
The simplest example:
It is 31 August, and you have:
- 30,000 PLN in the account,
- 40,000 PLN of unpaid invoices from clients,
- so your current assets are 70,000 PLN.
But you have to pay:
- 15,000 PLN to suppliers,
- 10,000 PLN in taxes and ZUS,
- 5,000 PLN in instalments/leases,
- so short-term payables = 30,000 PLN.
Your working capital in this example is:
70,000 PLN - 30,000 PLN = 40,000 PLN
DSO, the average time spent waiting for payment
DSO, short for Days Sales Outstanding, helps determine how long on average a company waits for money from its clients.
The longer a business waits for payment, the longer it finances its clients from its own funds.
It is worth watching not only the average for the whole company, but also the behaviour of each business partner.
Cash gap
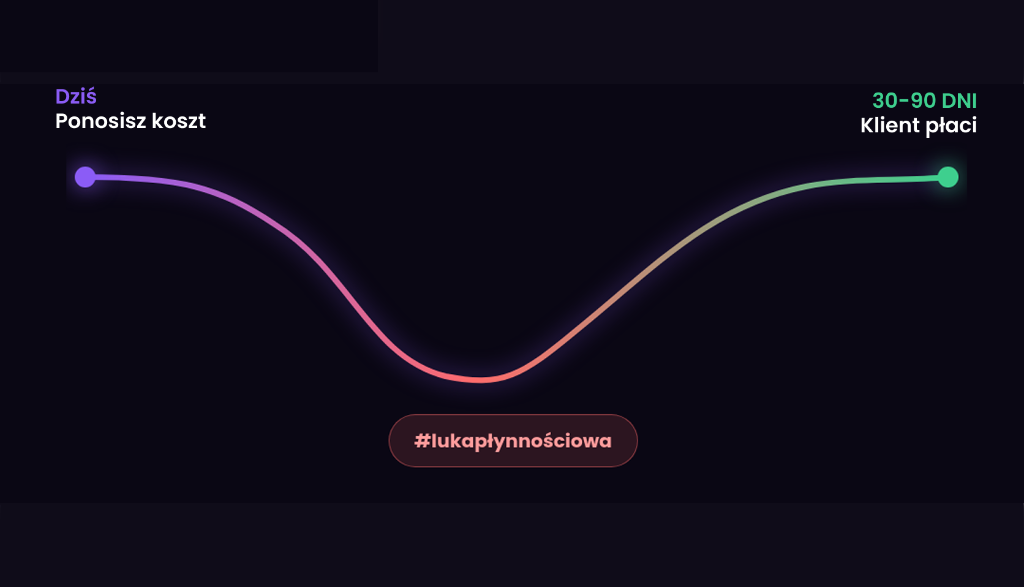
Cash gap shows the difference between the moment a company has to incur costs and the moment it receives money from the client.
For example, a company has to pay its team and subcontractors in May, but the client will settle the invoice only in July.
During that period the business finances the project from its own funds.
Output VAT and input VAT
Output VAT is the VAT arising from the company’s sales.
Input VAT is the VAT arising from purchases related to the business, which in certain cases can be deducted.
The difference between them affects the amount of VAT to pay, or a possible refund.
Depreciation
Depreciation lets you spread the cost of a given fixed asset over the period of its use.
That is why buying a machine, a car or another asset does not always appear in the financial result as a one-off cost in full.
It is one example showing why the accounting result and cash flows can look different.
The simplest example: you buy a printer for the company for 6,000 PLN.
The printer will serve the company not only in the month of purchase, but for several years. That is why, in certain cases, its cost does not have to be recognised all at once. It can be spread over time.
Let us assume, for a simple example, that we spread the cost over 3 years.
Then:
6,000 PLN ÷ 3 years = 2,000 PLN of cost per year
that is, about:
166.67 PLN of cost per month
This is depreciation. The company actually spent 6,000 PLN straight away, but in the books the cost of this purchase is recognised gradually over the period the device is used.
Financial result versus account balance
This is one of the most important differences a business owner should understand.
A company can have:
- high profit and little money, because clients have not yet paid,
- a lot of money and low profit, because an advance, a loan or funds relating to future periods have arrived in the account.
That is why a company’s condition should not be judged on the bank account alone.
How Administy organises this data
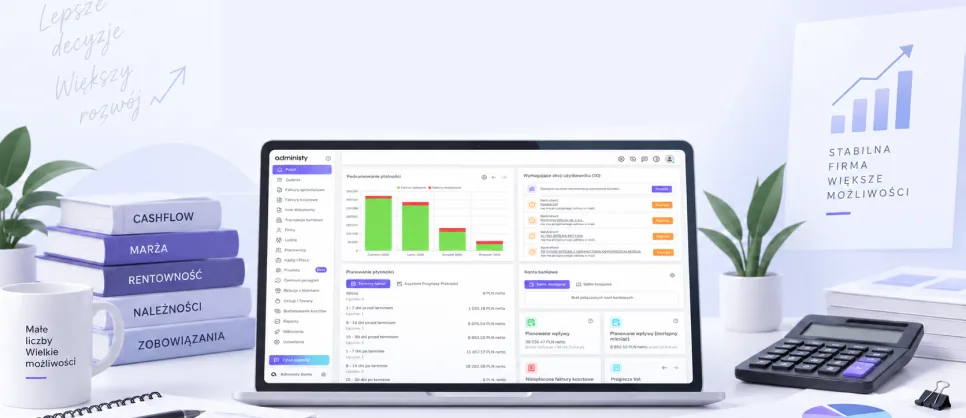
Administy combines financial information from invoices, payments, bank accounts, costs and projects.
The system supports, among other things:
- cash flow analysis,
- control of receivables and payables,
- forecasting of future inflows,
- analysis of business partners’ payment behaviour,
- cost budgeting,
- analysis of project profitability,
- converting working time into cost,
- assessment of future financial liquidity.
This means the business owner does not have to analyse each ratio in a separate spreadsheet. The data can be brought together in one place and used for day-to-day decision-making.
Summary
A business owner does not have to know all of accounting, but should understand the difference between:
- revenue and money received,
- profit and cash flow,
- margin and turnover,
- receivables and cash,
- profitability and liquidity.
It is these differences that decide whether a company merely looks good in reports, or truly has healthy finances and the funds needed for further growth.
Important information
This article is informational and educational. It does not constitute accounting, tax or financial advice.