Table of contents5 sections
Slow-moving stock in the warehouse: defining the problem
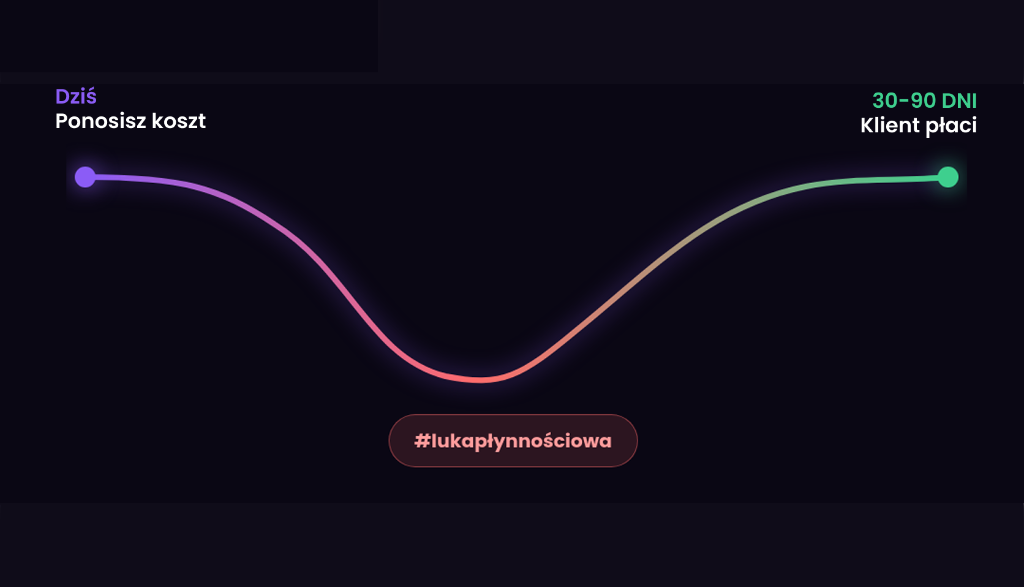
Slow-moving stock in the warehouse is not just a logistics problem. It is cash the company has already spent, but cannot use to settle invoices, pay employees, place new orders or grow sales.
We know what it is like when, on paper, a company holds a large asset base, while at the same time the account is running short of funds for current payables. The warehouse system shows thousands of products, but some of them have not moved for many weeks or months. More deliveries are ordered, costs rise, and the money stays frozen in stock that customers are not buying.
The problem often builds up gradually. One oversized purchase does not have to endanger the company, but regularly ordering goods without analysing turnover, margin and future inflows can lead to a situation in which the business has a full warehouse and, at the same time, not enough liquidity.
That is why inventory management should not be limited to checking how many units are in stock. You also need to know:
- how much money is frozen in individual product groups,
- how long goods stay in the warehouse,
- which products turn over, but generate too little margin,
- which items do not sell despite repeated promotions,
- when the company will recover the funds from stock it has already bought,
- whether planned inflows will be enough to restock.
Stock in a warehouse is not an asset — it is frozen cash that becomes liquid only once it has been sold, invoiced and paid.
Slow-moving stock in the warehouse: symptoms and risks for the company
Slow-moving stock rarely appears suddenly. The company gradually gets used to a growing number of products, explaining it by seasonality, a wider offer or the need to guarantee availability. The problem begins when there is no real demand behind the stock.
There is no money despite a high warehouse value
The business owner sees a large value of goods, but cannot use it to pay invoices. A product in the warehouse is not cash. It becomes cash only once it has been sold, invoiced and the client has actually paid. So a company can look good in the reports and still have trouble settling its current payables.
The company keeps placing orders without knowing real turnover
Purchases are often made on the basis of past habits, sales reps’ forecasts or fear of running out of a product. If decisions do not take current sales and existing stock into account, the company may reorder goods it already has too much of. As a result, cash is frozen twice: in the old stock and in the new delivery.
Storage costs keep rising
Slow-moving goods take up space, require handling and generate extra costs. These may include, among others:
- warehouse space rent,
- stock insurance,
- the work of people responsible for the warehouse,
- stocktaking and stock level control,
- transfers between warehouses,
- loss of product value,
- the risk of damage, expiry or going out of fashion.
The longer a product stays unsold, the larger the share of its original margin that is swallowed up by holding costs.
The company cuts prices without knowing the minimum margin
When stock starts to pile up, the natural reaction is to launch a promotion. The problem appears when the discount is set without taking the full cost of the product into account. Sales may improve turnover, but not necessarily the financial situation. If the price does not cover the purchase cost, storage, sales handling and delivery, the company is merely turning slow-moving goods into a loss.
New products are financed with credit or deferred payments
A lack of cash often leads to working capital loans, factoring or longer payment terms with suppliers. Such solutions can help in the short term, but they do not remove the source of the problem. If the company keeps buying more than it can sell, external financing merely postpones the moment when the lack of control over stock becomes a serious threat to liquidity.
How to release the cash frozen in the warehouse?
Solving the problem requires combining warehouse, sales and financial data. Information about the number of units alone is not enough. You need a process that lets you assess stock in terms of its value, turnover, profitability and impact on cash flow.
1. Split stock by turnover and value
The first step is to divide products into groups. Not every slow-moving item calls for the same reaction. It is worth separating:
- fast-moving products,
- products sold regularly, but in small quantities,
- seasonal products,
- products with declining sales,
- non-moving products,
- stock with a high unit value,
- goods at risk of losing value.
This lets the company determine which items are really blocking the most cash. Often a small number of products accounts for a large share of the value of slow-moving stock.
2. Calculate the full cost of holding a product
The purchase price is not the only cost of goods. The analysis should also include: transport and goods receipt, storage, the cost of capital frozen in stock, logistics handling, returns and complaints, potential markdowns and the risk of losing value. Only after taking these elements into account can you decide whether it is better to keep waiting to sell at the original price, or to release cash faster through a controlled price cut.
3. Prepare a separate plan for non-moving stock
Goods that have not sold for a long time should not be left without a decision. For each product group you need to specify a concrete course of action:
- a time-limited promotion,
- bundle sales with a fast-moving product,
- an offer for a different customer group,
- wholesale or clearance of the stock,
- a return or exchange with the supplier,
- moving to another sales channel,
- withdrawing the product from the regular offer.
What matters most is that the decision takes into account not only the possible revenue, but also the value of the cash recovered and the cost of further storage.
4. Link purchases to the cash flow forecast
A new order should be assessed not only by the purchasing department, but also in terms of future liquidity. Before approving a delivery, it is worth checking:
- how much cash the company currently has,
- what inflows are realistically expected,
- what payables must be settled in the coming weeks,
- what part of the current stock remains unsold,
- when the new goods should start generating revenue,
- whether the company can afford to freeze more funds.
How did we solve a similar problem at Administy?
While running an agency, we did not store physical goods, but we faced a very similar financial mechanism.
The equivalent of stock for us was:
- unused licences and subscriptions,
- services bought in advance,
- reserved employee hours,
- subcontractors already paid,
- costs incurred before the invoice was issued,
- resources prepared for a project that was delayed,
- expenses that were meant to bring revenue only in the future.
At first glance, these were justified operating costs. Only after linking them to inflow dates did it turn out that part of the cash stayed frozen much longer than we assumed.
We made the mistake of analysing costs and revenue separately. We knew how much we had spent and how many invoices we had issued, but we lacked a single picture showing when an incurred cost would actually come back to the company as cash.
That is why at Administy we organised costs by: category, supplier, project, period, responsible person, payment status and the nature of the cost (one-off / recurring). We then linked them to the inflow forecast and to clients’ actual payment habits.
Thanks to this, we could notice earlier that:
- we are paying for a resource that is not being used,
- a project cost has been incurred, but the invoice has not yet been issued,
- a client will probably pay later than the due date suggests,
- planned inflows will not cover the nearest payables,
- too large a share of funds was committed before revenue was received.
The same mechanism can be applied in trade. A slow-moving product should be visible not only as a warehouse item, but as a specific amount of frozen cash that affects the ability to place further orders and settle payables.
A full warehouse cannot replace financial liquidity
Slow-moving stock does not always mean the company bought the wrong products. Sometimes the source of the problem is a lack of current data, an overly optimistic sales forecast, or purchasing decisions that are not linked to the financial situation. A full warehouse will not replace cash in the account — until the goods are sold and paid for, they remain frozen capital that blocks the company’s growth.